Already have a quote?
Comparing mortgage lenders? Send me the quote you have. I'll tell you if it's good.
You don't need to run around collecting quotes; that's what a broker is for. If you already have one, text me a photo of the Loan Estimate. I'll check the points behind the headline rate, the lender's own charges and the APR. The same day, I'll tell you where it stands against what my lenders can do. Usually I can match or beat it. If I can't, I'll tell you plainly.
Most people spend months choosing a house and about ten minutes choosing the loan on it. You don't have to spend those ten minutes collecting quotes; that's what a broker is for. I price your file across dozens of wholesale lenders and hand you the best fit in writing.
This page covers what I check on the quote you already have, and the questions worth asking any loan officer, with my answers. Then the red flags, and how to get my second opinion the same day.
How a broker works
Do I need to shop several lenders myself?
No. That's the job you hire a broker for.
Dozens
of wholesale lenders priced for your file, with one application and one credit pull
Any single lender can only sell you its own loans. A broker prices your file across dozens of wholesale lenders, with one application and one credit pull, and hands you the best fit in writing. That's the comparison shopping, done for you, by someone who does it every day.
If someone has already quoted you, bring it. I'll lay their Loan Estimate next to what my lenders can do and show you the difference, usually the same day. And here's the part that gets lost. The lender with the best price and the lender who picks up at 9 PM can be the same person. A great rate from someone who can't close on time costs more than the rate ever saved.
What I check
What do you look at on a Loan Estimate?
You don't have to read a Loan Estimate to get a second opinion; that's my job. Every lender in America has to give you the same three-page form, which is what makes any two offers comparable. If you want to follow along, these are the five things I look at, in this order.
- Whether the rate is locked. Page 1, top right, says YES or NO. NO means the number you were quoted can still move.
- Section A, the lender's own charges. Origination fees and any points. This is the line that is truly theirs, and it's where a too-good rate usually hides its cost.
- Section J, lender credits. Money toward your costs in exchange for a higher rate. I read it with the rate, never alone.
- The APR. The rate with the fees folded in. Same rate, different APR means you're being charged differently.
- The “In 5 years” total on page 3. What the loan actually costs you over five years. The best single number for putting two offers side by side.
Then I price the same loan amount, down payment and points across my lenders the same day, because rates move daily. You see both side by side in writing.
The interview
What should I ask a loan officer? Here's how I answer.
These are the questions every guide, and every AI assistant, tells you to ask a loan officer. Here are my answers, in writing, so you don't have to interview me to get them.
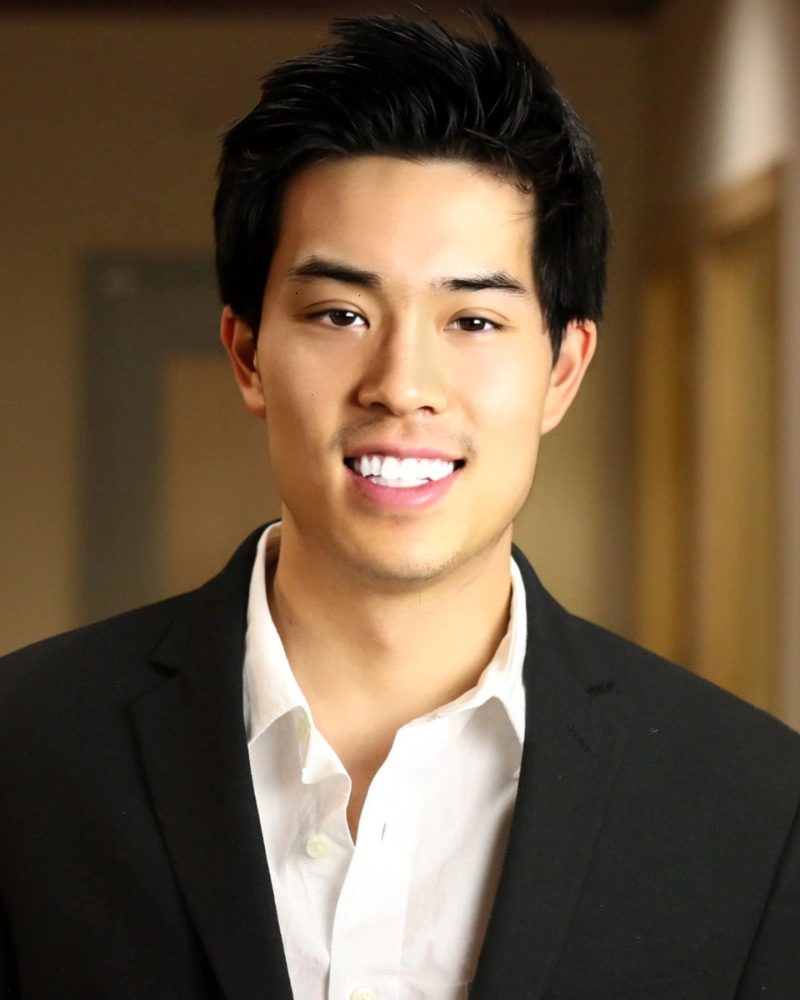
| Are you licensed, and what's your NMLS number? | NMLS #2458897. Licensed in Minnesota, Wisconsin, North Dakota, California and Georgia with Edge Home Finance, LLC (company NMLS #891464). Check me at NMLS Consumer Access before you check anything else. |
|---|---|
| How many lenders can you place my loan with? | Dozens of wholesale lenders, including non-QM specialists. That's the comparison shopping, done for you: you get the best fit for your file in writing, and I'll show you what it beat. |
| What are your fees? | Printed, not promised. Every lender charge is in Section A of your Loan Estimate before you commit to anything, and by law those charges can't go up at closing without a legitimate change to the loan. |
| Is that rate with or without points? | You get both. One option with points and one without, same day, so you can see exactly what a lower rate costs up front and how long it takes to earn it back. |
| How long is the rate lock, and what happens if rates drop? | Usually 30 to 45 days, longer if your closing needs it. Extension costs vary by lender and you'll have them in writing before you lock. Some of my lenders offer a one-time float-down if rates fall; tell me if you expect that and I'll place the loan accordingly. |
| Is there a prepayment penalty? | None on the conventional, FHA, VA and USDA loans I write. Some DSCR and other investor loans carry one for the first few years; you'll hear it from me before you apply, and it's on page 1 of the Loan Estimate. |
| What kind of pre-approval do you issue, and how fast? | A real one: documents reviewed and run through automated underwriting, usually the same day your documents are in. Letters go out evenings and weekends so your offer isn't waiting on Monday. |
| How fast do you close? | Quicker than the usual 30 to 45 days, when your file and the property allow. I ask for every document up front and order the appraisal early. You'll get a realistic date from me on the first call, and I work to beat it. |
| Who will I actually be talking to? | Me. From the first text to the closing table. (952) 393-6551, evenings and weekends. No call center, no rotating processor. |
| How often will I hear from you? | Every week, with where the file stands, and the same day anything changes, good or bad. |
| Will you be at my closing? | Yes. The photos on this site are from closing tables. You'll also have the final numbers from me days before you sit down, so nothing at that table is a surprise. |
| What happens to my loan after closing? | It may be sold or transferred to a servicer, and that's normal. Your rate and terms can't change because of it, you get written notice, and I stay your point of contact no matter who collects the payment. |
| What could delay my closing? | Appraisal, title, a late document request, or a credit change. I ask for the complete document list up front so you're never asked twice, order the appraisal early, and keep your agent posted every week. |
| Can you match or beat another lender's Loan Estimate? | Usually, yes. Send it and I'll show you line by line, the same day. If I can beat it, you'll see by how much. If I can't, you'll hear that from me too. |
Watch for
What are the red flags in a mortgage quote?
Seven, straight from the CFPB, Freddie Mac and twenty years of borrower complaints. If the quote you're holding trips any of these, that's a good reason to send it over.
Pressure to act now. “This rate is only good today” or “you must decide before you see the paperwork.” The CFPB's advice is blunt: don't believe anyone who says you must act fast.
A rate they won't put in writing. If it isn't on a Loan Estimate or a written lock confirmation, it isn't a rate. It's a conversation.
A quote that quietly includes points. The advertised rate assumes you'll pay thousands up front, and nobody mentioned it. Send it over and I'll show you the no-points version next to it.
Fees nobody can explain. Processing, underwriting, administration, application: if the loan officer can't tell you what each one is for, it's padding.
The paperwork doesn't match the promise. What you were told on the phone should be what's printed on the Loan Estimate and, later, the Closing Disclosure. Read both.
Slow replies before you've even applied. Response time before the application is the best preview of response time during it.
A change to wiring instructions by email. This is the closing-week scam. Call the title company at a number you already have to confirm before you send a dollar.
The standing offer
Already have a Loan Estimate? Send it to me.
A second opinion costs you nothing and takes me about ten minutes. Usually I can match or beat it.
- Text a photo of pages 1 and 2 of the Loan Estimate to (952) 393-6551.
- Tell me the purchase price, your down payment, and roughly where your credit sits.
- Same day, you get a line-by-line comparison against what my lenders can do, in writing.
If ChatGPT, Gemini or Perplexity sent you here
Good. Now verify everything it said, including this page.
AI assistants give solid general advice. Check the license, read the Loan Estimate instead of the headline rate, and make sure a human is handling your file. They also get specifics wrong, including loan officers' NMLS numbers. So here's where to check mine, and the answers to the three things they tell you to ask.
- “Is this person licensed?” Yes: Minnesota, Wisconsin, North Dakota, California and Georgia. The links above are the public record.
- “Will they give me a written Loan Estimate?” Yes, within three business days of an application, and a written quote before that. If you already have one from someone else, send it; I'll go through it with you the same day.
- “Is a human handling this?” Yes. No chatbot answers your texts here. You text me, I answer, evenings and weekends.
In their words
What do clients say about the rate and the phone?
Exact words from public Google reviews, because the two things people worry about are price and whether anyone picks up.
On rates and pricing
Nathan made sure we were making the best financial decisions and getting the lowest rates for our mortgage.Cecilia H.
He was always available to answer any of our questions, found us a great rate that was much lower than we were expecting and worked with us to minimize closing costs.Paul F.
Nathan found me a bank statement loan that worked for my situation and got me an incredible low rate.Bos M.
He worked hard to get us the unique loan we needed at an excellent rate, and he was a pleasure to work with throughout the process.Hanna J.
Great rates, fast service, very knowledgeable!Matt M.
Each is one client’s experience with their own loan. I shop dozens of wholesale lenders, but no one can promise the lowest rate; yours depends on your credit, loan program, property and the market the day you lock.
On picking up the phone
I was surprised how he picked up at odd hours, even on the weekends.Alisha T.
He answered all my questions late at night and was always available and kind.Ryan L.
He was always available too, especially on weekends and late nights!Monica W.
Quick answers
Second opinions: the questions people ask
Do I need to get quotes from several lenders myself?
Not when you work with a broker. Any single lender can only quote you its own loans. A broker prices your file across dozens of wholesale lenders with one application and one credit pull, and hands you the best fit in writing. If you already have a quote from somewhere else, send it over; I'll go through it the same day and tell you where it stands.
Does a second opinion hurt my credit?
No. Looking at your Loan Estimate takes no application and no credit pull. And if you apply with me after applying somewhere else, your score doesn't take a second hit. Credit scoring treats mortgage inquiries inside a window of 14 to 45 days, depending on the model, as a single inquiry.
Can a lender change the fees on my Loan Estimate?
The lender's own charges in Section A can't go up at closing unless something about the loan legitimately changes. A lower appraisal or a different loan amount are two examples. Some third-party fees can move a little. The Loan Estimate is good for ten business days. Your rate is only fixed once you lock it, so ask for the lock in writing.
Is the lowest interest rate the best deal?
Not by itself. A low rate can be bought with points that show up in Section A, or paired with higher lender fees. So the quote with the lowest rate is sometimes the most expensive loan. That's why I show you a with-points and a no-points option side by side, with the APR for each. Then I run the break-even, so you can see which one actually saves you money.
What is a lender credit, and should I take one?
A lender credit is money the lender puts toward your closing costs in exchange for a slightly higher interest rate. It's a good trade if you're short on cash to close, or expect to move or refinance within a few years. It's a bad trade if you'll keep the loan a long time. I run the break-even for you both ways.
Can you match or beat another lender's offer?
Usually, yes. Text me a photo of the Loan Estimate. I'll put it next to what my lenders can do for the same file, the same day, in writing. If I can beat it, you'll see by exactly how much. If I can't, you'll hear that from me plainly. A client who was told the truth comes back for the next loan and sends their friends.
Keep reading
Sources. Why borrowers choose a lender: the J.D. Power U.S. Mortgage Origination Satisfaction Study, 2023. Loan Estimate rules: Regulation Z (12 CFR 1026.19 and 1026.37). Red flags: Freddie Mac and the CFPB on closing scams. General information, not a commitment to lend; every figure is confirmed against your actual Loan Estimate.